Hotel Rate Parity and Distribution Costs
Let this article serve as an answer to some questions raised by hoteliers regarding intermediation costs, particularly when Booking.com accounts for more than 60% of sales in many cases.
I am not particularly in favour of hotels maintaining rate parity across their various distribution channels. Among other reasons, distribution channels are not all the same: they do not apply the same intermediation cost parity, nor do they have the same positioning in every market.
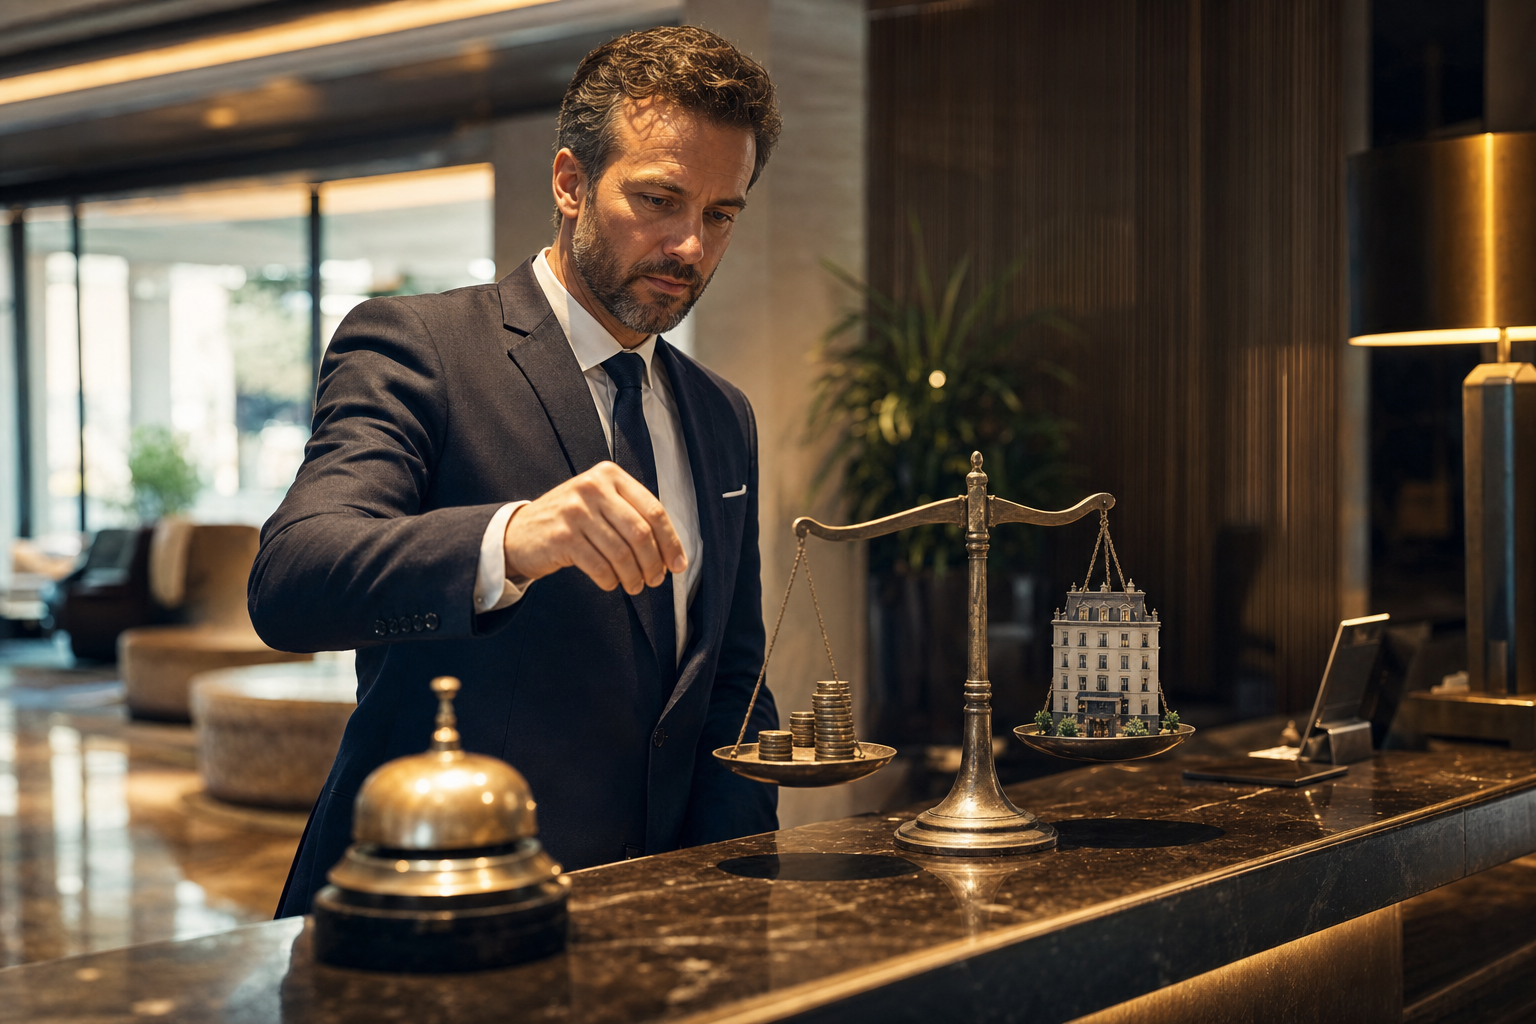
The cost of intermediation, whether in the form of a commission or a margin applied to the contracted net rate, must be commensurate with the value delivered by the channel itself.
The value delivered by a channel can and should differ from one hotel to another, based on its segmentation and, especially, its level of market positioning (that of the hotel, of course).
A hotel establishment with strong brand positioning, as is the case with major hotel chains, does not depend on large travel agency networks and major distributors, and is therefore generally inflexible regarding the commissions to be applied. It is a matter of “take it or leave it”, to which agency networks must yield, as it is the customer who demands these products; and if the point of sale cannot meet their requirements, the customer will find another way, either by booking directly with the hotel chain or by going to another agency that does offer that product.
In the online world, there are no major differences beyond those set by the hotel establishments themselves. The point is that, in the offline world, what brand is, online, positioning is.
Even without being a major brand, a hotel establishment can achieve a certain degree of online positioning, making its dependence on major online distributors relative, or at least necessary only in those markets where it is difficult for the hotel to achieve online positioning.

AI is only as smart as the context you give it. HotelGEX gives it your whole hotel.
Guests, Revenue, operations, F&B, Groups & Events and Management connected in one intelligent context, so HotelGEX AI can understand what is really happening across your hotel.
Full hotel context.
In the first case—that is, where the hotel has good positioning in markets considered strategic, and where its dependence on online distribution channels is lower—the value of those channels should logically be lower and, consequently, so should the cost of intermediation.
In the second case, where the hotel has limited positioning, while an online distributor may have a strong presence in that particular segment or market, the value of the intermediary to the hotelier is then justified. As such, any intermediation cost, being a variable cost, should rightly be accepted by the hotel.
Ultimately, it comes down to a question of “Do Distribution Channels bring me the Customers that I, as a Hotel, cannot secure through my own means?”
If, as I see it, the cost of intermediation should be relative to the establishment’s level of positioning in certain markets, the applicable price should be set by the market, not by the distribution channel itself.
I have never been in favour of “merchant” models (a margin applied to a net rate), in which we know they earn more from intermediation than the hotel establishments themselves do from delivering the service. The main reason is that I believe the hotel must retain control of its positioning and, consequently, of the final rate at which its rooms are sold.
The only regulator of the selling price, together with the hotelier’s instinct, is the market itself, and the distribution channel should never be the one to raise the property’s price in order to generate higher revenue.
In any case, this is the price hoteliers must pay for not having the positioning that some—not all—online distribution channels currently enjoy. Of course, this approach adopted by some online intermediaries is a case of “short-term gain, long-term pain”, as more and more establishments are taking control of their distribution, their selling price and their positioning. We already know of one intermediary facing serious difficulties in surviving.
Ultimately, the dilemma facing the hotelier is:
- Invest in positioning.
- Pay commissions forever.
More and more establishments are opting for the former; I can attest to that.
How can the cost of intermediation be passed on to the intermediary itself? By allowing the market to regulate its margins.
This article ends here. The archive does not.
Lead Hospitality brings together 1200 English articles published since 2018: years of experiences, decisions and lessons you can keep exploring.
What would you like to explore next?
Choose a direction and keep reading around what you want to solve, learn or challenge.